There is a perception that the selloff in hyperscaler and data center debt is an indictment of the AI trade and confirmation that the market doesn’t believe tech companies can capitalize well enough on their massive capex investments.
But when you ask credit investors, their explanation for widening credit spreads is much simpler: excessive supply.
“It is unquestionably an issue of supply,” one IG syndicate banker said. “Hyperscaler debt trading wider is not because you think that Microsoft or anyone else is going to default, or you think that the AI ecosystem is fraught with risk — it’s purely a market that is incredibly saturated.”
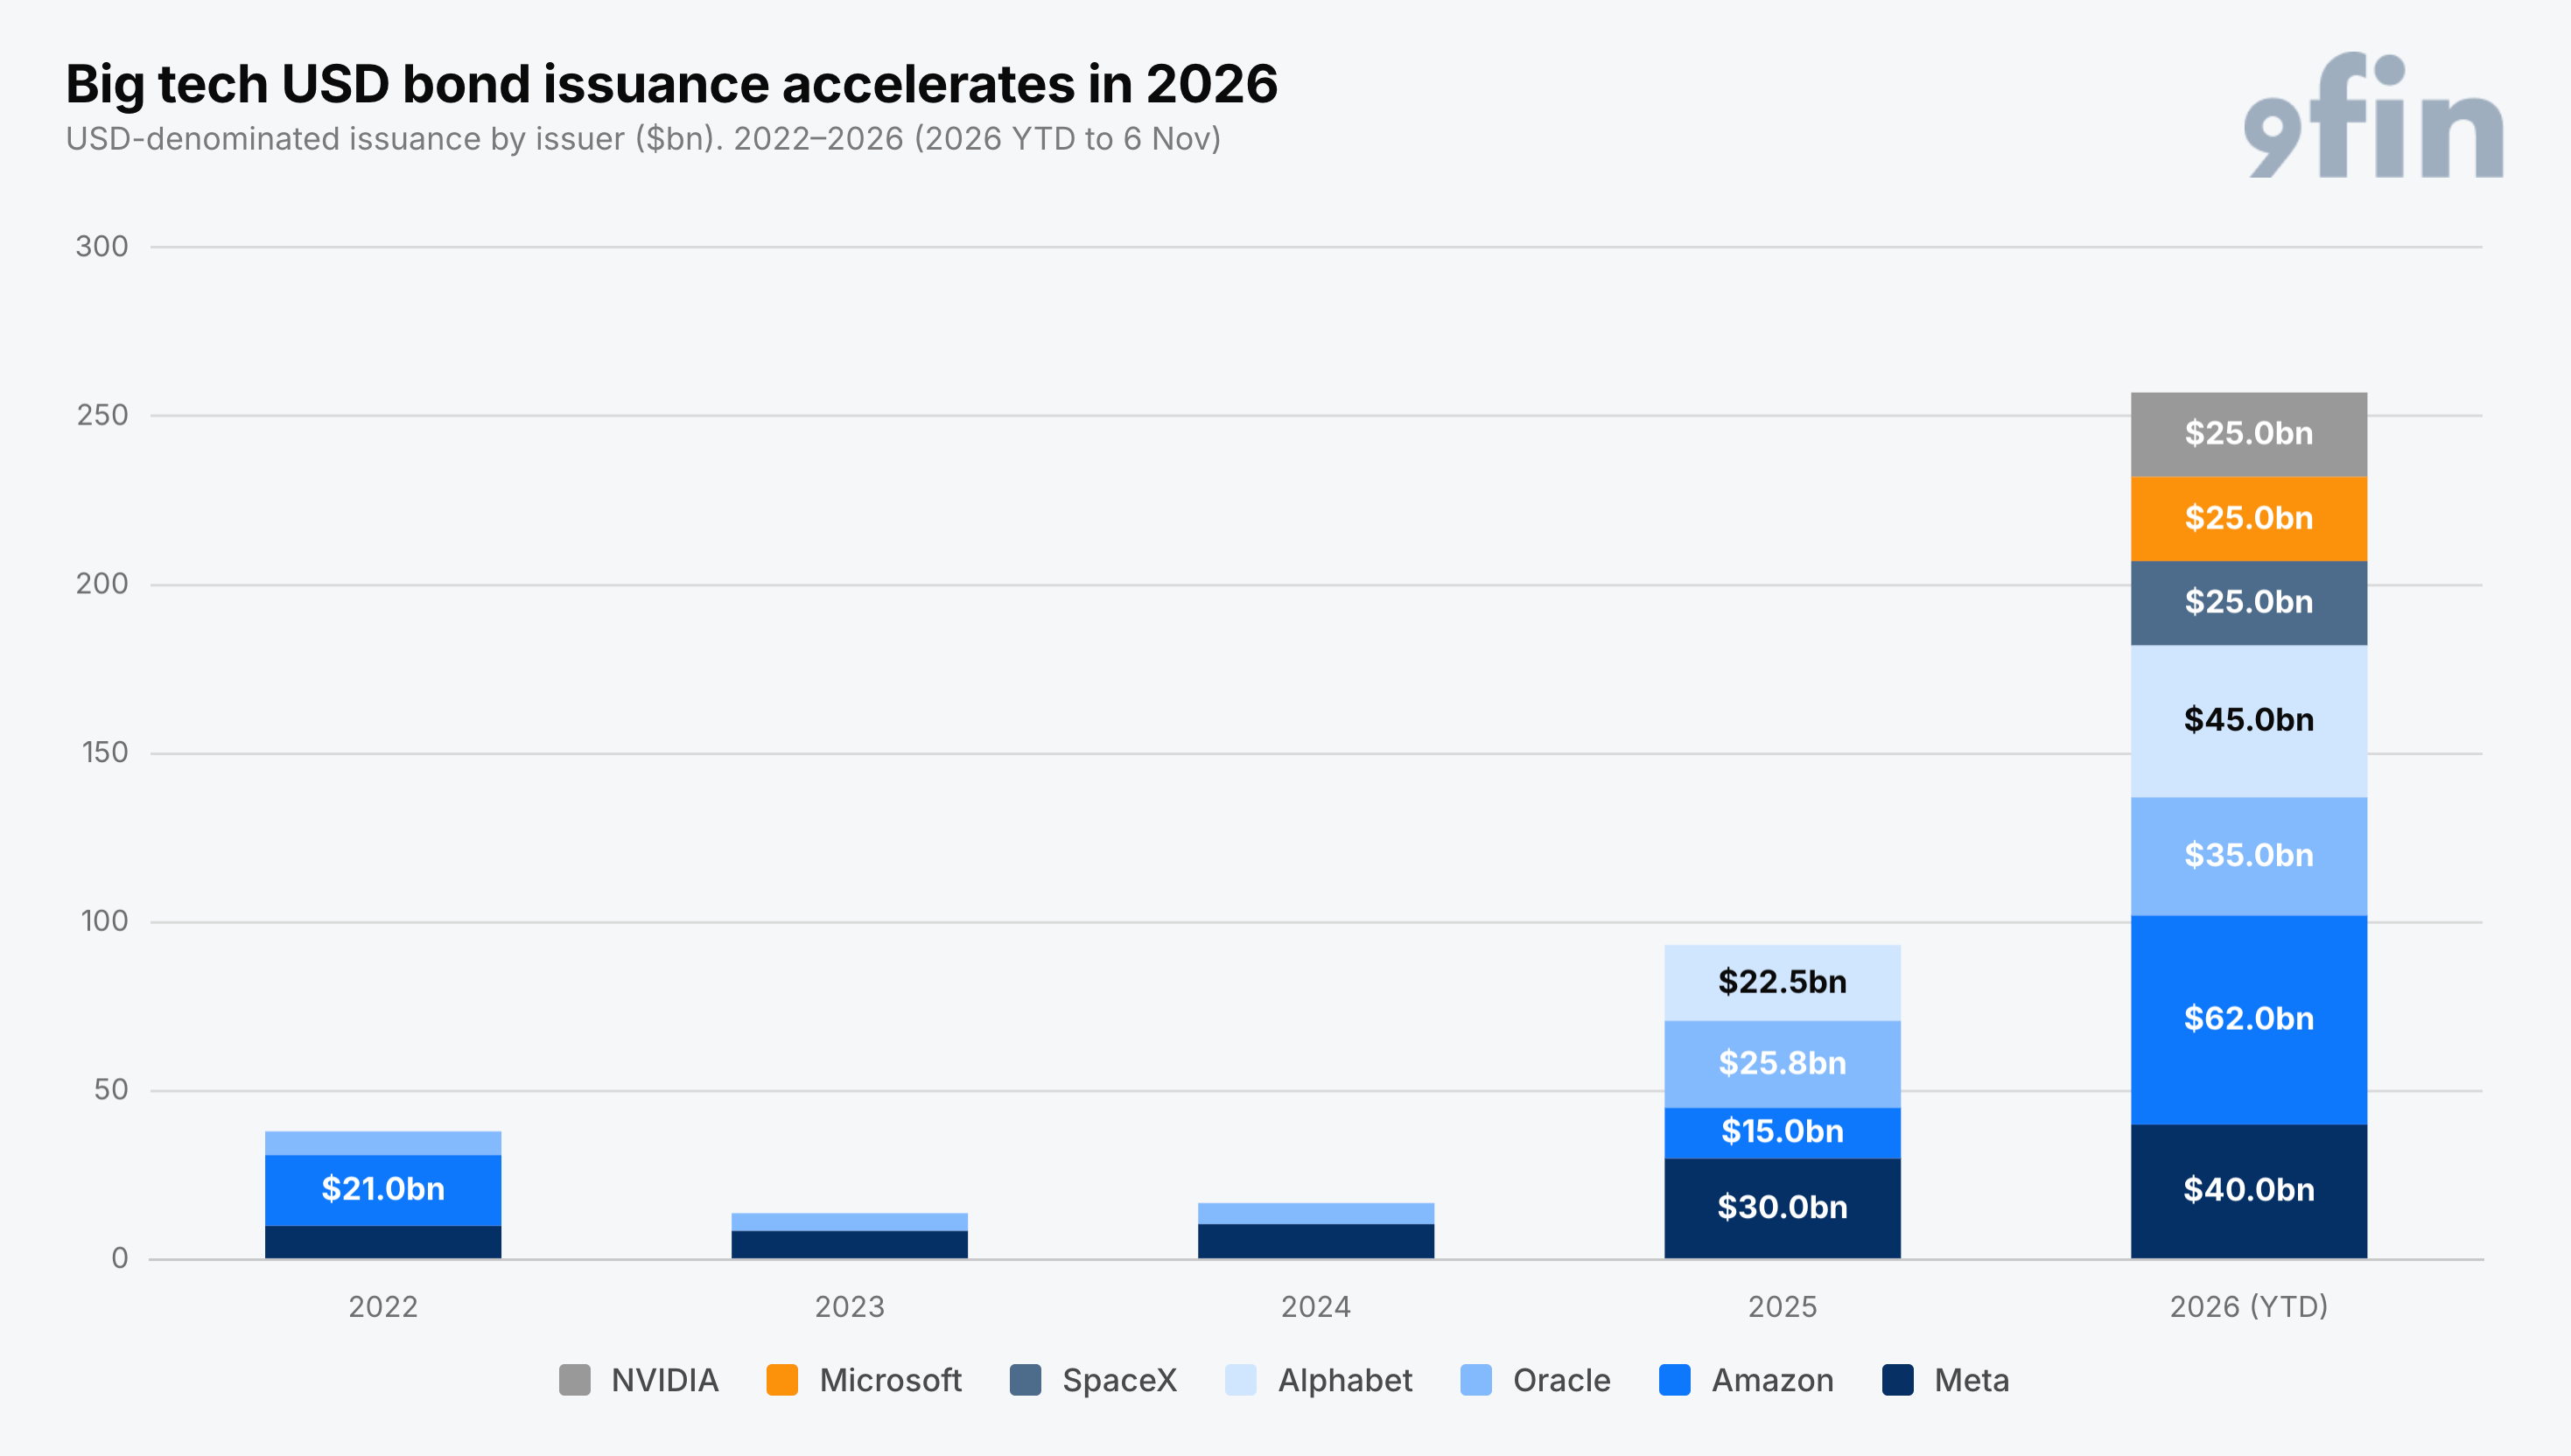
Seven tech issuers combine for more than $250bn of USD supply YTD (source: 9fin)
On the surface, credit spreads are an indicator of risk, and widening spreads signal that risk is building. The evidence of that is seemingly everywhere. Triple-A rated hyperscaler bonds are offering double-digit concessions, chip financings marketed to private investors are widening out, and some data center debt deals are getting shelved until markets stabilize.
But the credit market is not the equity market. As stocks sold off Thursday (5 November), newly printed deals from Meta and Oraclecontinue to...