Ahead of the Bastille Day holiday volumes picked up as issuers took advantage of relative stability in underlying markets at the beginning of the week. A busy one was expected ahead of the summer lull in activity — in the last four years the week following the French holiday has seen just €10.3bn raised on average.
However, the renewal of US military action against Iran unsurprisingly resulted in higher oil prices at around $76.25/bbl early on Friday but below a midweek peak above $80, which weighed on risk appetite with new issue activity falling off rapidly as a result.
This also put upwards pressure on government bond yields. Ten- and 30-year US treasury yields exceeded the psychological 4.50% and 5.00% barriers to end at 4.53%. and 5.05% respectively as potential inflationary concerns extended into Europe after equity markets gave back several days of gains with 10-year Bunds ending at 3.03% and Gilts at 4.90%.
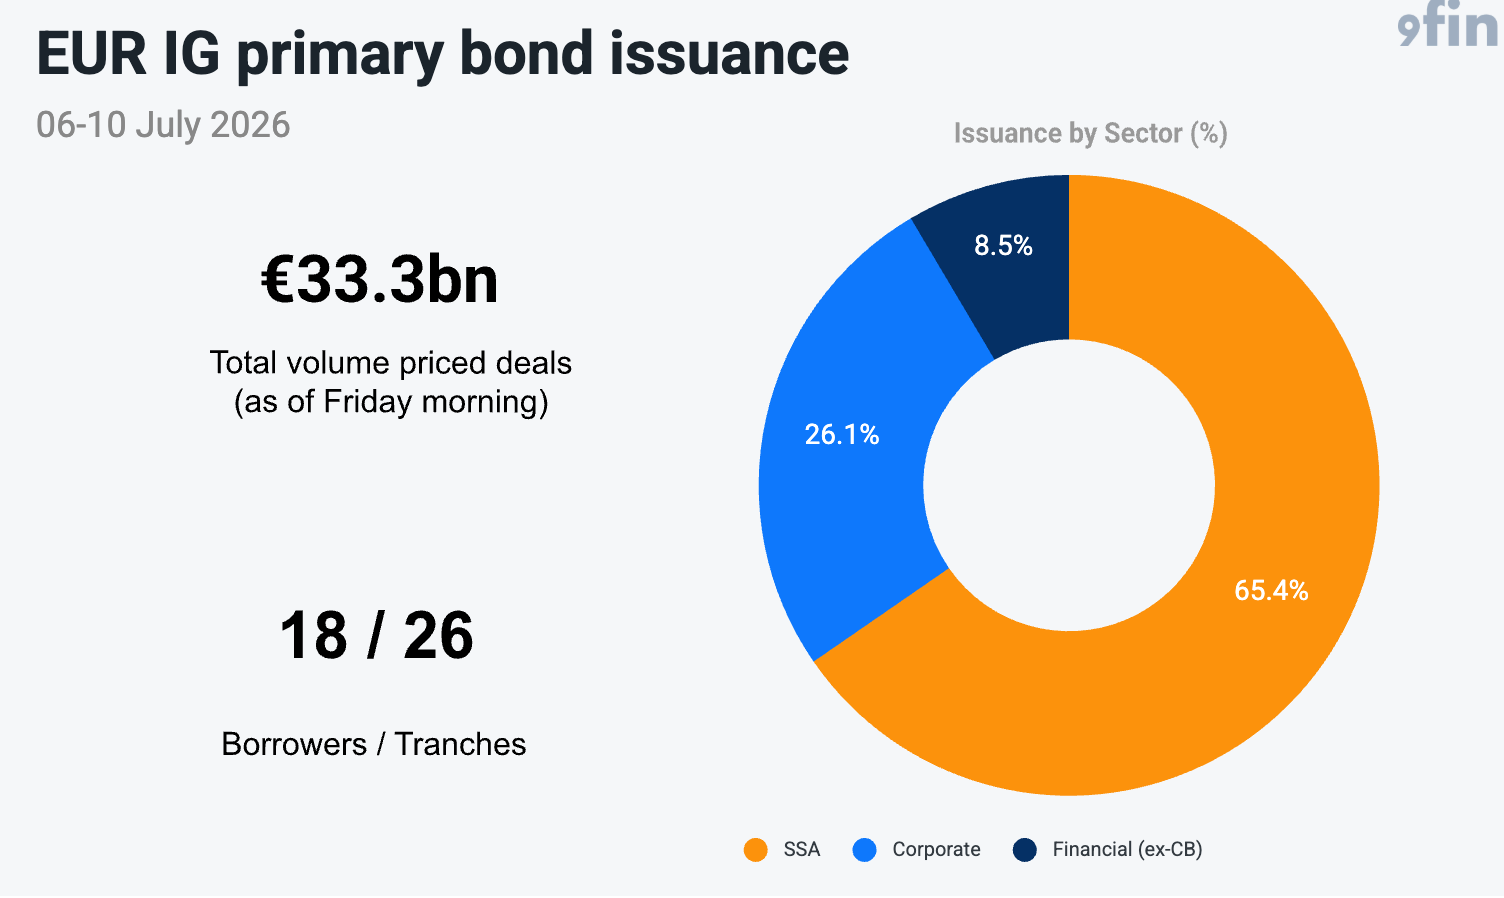
SSA supply dominated as it reached €21.8bn followed by corporates, including no less than three inaugural issuers, at €8.7bn, with just €2.8bn of financial issuance. This took the weekly total to €33.3bn (as of Friday morning) compared to €21.7bn the previous week.